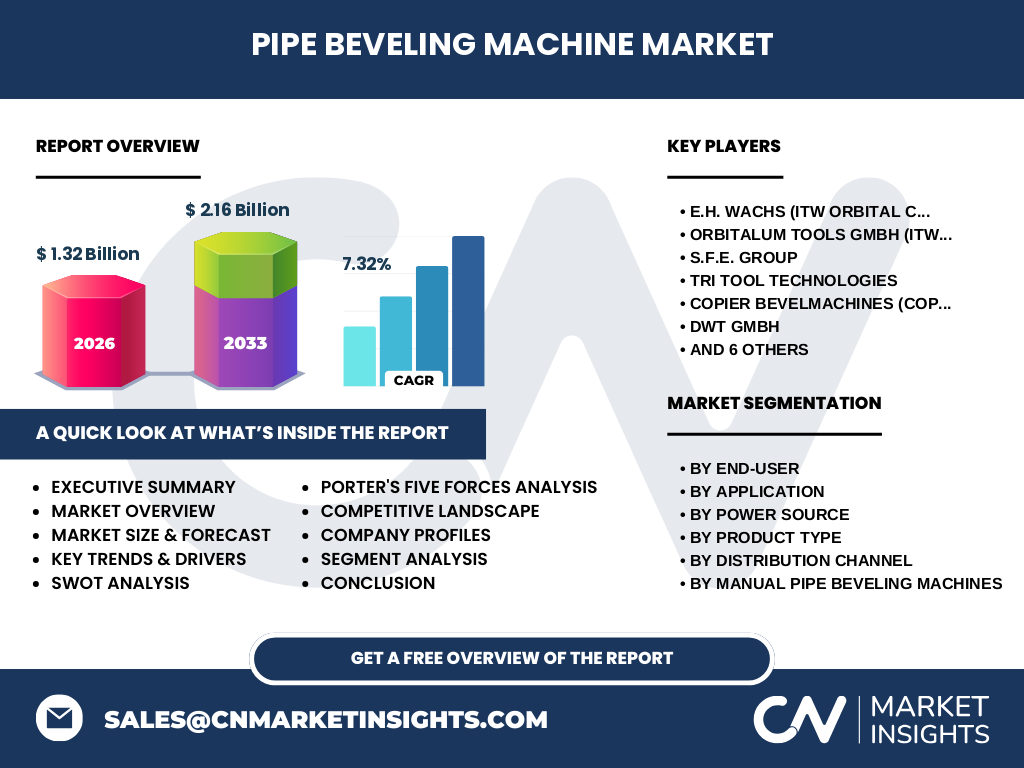
Market overview of the Pipe Beveling Machine Market
The Pipe Beveling Machine Market is valued at 1.32 Billion in 2026, encompassing critical preparation equipment used prior to welding across structural metals and alloy pipelines. This sector ensures weld integrity by machining precise pipe ends, serving as an indispensable manufacturing and maintenance pillar for heavy industrial fabrication.
Structural Growth Drivers and Market Restraints
Our analysis indicates that stringent safety regulations by bodies like OSHA and ASME drive demand, while the high initial capital expenditure for Computer Controlled Machines acts as a market restraint. Opportunities thrive in automation upgrades across major fabrication yards.
Emerging Trends in the Pipe Beveling Machine Market
The industry is experiencing a rapid shift toward Battery Operated Portable Machines and IoT-enabled units. Fabricators demand untethered operational flexibility on remote energy sites, minimizing setup times while enhancing precision beveling on exotic corrosion-resistant alloys.
COVID-19 Impact Analysis and Recovery Trajectory
Pandemic-related supply chain disruptions for raw steel and critical electrical components temporarily stalled industrial manufacturing lines. However, a robust recovery trajectory has pushed the market toward a projected valuation of 2.16 Billion by 2033, driven by delayed infrastructure projects resuming.
Competitive Benchmarking and Strategic Dynamics
The competitive landscape features high market concentration among specialized innovators like E.H. Wachs (ITW Orbital Cutting & Welding) and Orbitalum Tools GmbH (ITW). These leaders maintain dominance through proprietary quick-change mounting systems and robust global distribution networks.
Executive Summary of Key Findings
Based on our research, the Pipe Beveling Machine Market will expand at a 7.32% CAGR from 2027 to 2033. Growth is anchored by surging energy infrastructure demands, with Portable Pipe Beveling Machines leading product category adoption across field-machining applications.
Market Forecast from 2027 to 2033
Our forecasting models project the market to scale from 1.32 Billion in 2026 to 2.16 Billion by 2033. This 7.32% CAGR reflects accelerated investments in cross-border natural gas pipelines and offshore fabrication yards requiring high-precision weld preparation.
Segmentation Analysis Across End-Users and Applications
The market is segmented by end-user into Industrial, Commercial, and Other End-Users, while applications span Oil And Gas, Power Generation, and Shipbuilding. Oil And Gas commands the largest application share due to extensive pipeline laying requirements.
Regional Market Analysis and Geographic Distribution
Geographic performance highlights North America and Asia-Pacific as primary revenue centers. Rapid industrialization, heavy shipbuilding in East Asia, and extensive midstream oil infrastructure upgrades across North American shale plays heavily influence regional volume consumption.
In-Depth Regional Review of Key Markets
Asia-Pacific exhibits the fastest regional growth rate, propelled by massive chemical processing plant construction in China and India. Meanwhile, European markets emphasize stringent ergonomic and safety standards, favoring advanced Pneumatic and Electric portable units.
Company Profiles and Strategic Positioning
Industry stalwarts such as Tri Tool Technologies and S.F.E. Group leverage comprehensive product portfolios spanning manual to automated solutions. Meanwhile, regional players like Shanghai Chuanli Industrial Co. Ltd. (KEPUNI) capture cost-sensitive markets with robust, heavy-duty industrial grade machines.
Porter's Five Forces Analysis of Competitive Pressures
Bargaining power of buyers remains moderate due to specialized machining requirements, whereas threat of substitutes is low given the irreplaceable nature of mechanical weld preparation. High R&D costs create a significant barrier to entry for new market aspirants.
SWOT Analysis of the Pipe Beveling Machine Industry
Key strengths include high precision and durability; weaknesses involve high maintenance costs for hydraulic units. Opportunities lie in automated shipbuilding applications, while threats stem from raw material price volatility affecting heavy-gauge carbon and alloy steel components.
Value Chain Analysis from Raw Materials to End-Users
The value chain initiates with alloy steel and motor component sourcing, progressing through precision CNC machining and motor integration by manufacturers like Copier Bevelmachines. Distribution occurs via specialized industrial dealers before reaching end-user fabrication shops.
Investment Insights and High-Potential Areas
Strategic investors should target manufacturers specializing in Computer Controlled Machines and lightweight Battery Operated Portable Machines. These high-margin segments align with the broader industrial automation push to eliminate human error in weld beveling.
Conclusion and Key Takeaways
The Pipe Beveling Machine Market represents a stable, high-growth industrial sector expanding to 2.16 Billion by 2033. Success relies on technological integration, specifically embedding programmable controls and lightweight portable designs to meet complex field-welding demands.
Research Methodology and Data Triangulation
Baseline estimates are triangulated by combining global trade registry data, primary stakeholder interviews with application engineers at DWT GmbH and Exact Tools Oy, and secondary macroeconomic indicators regarding global capital expenditure in energy infrastructure.
Scope of the Report and Coverage Parameters
This report covers global market dynamics for beveling equipment from 2026 to 2033, evaluating four power sources, four product types, and multiple end-user verticals. Excluded from this scope are stationary machine tools utilized strictly for generic metal turning outside pipe fabrication.
Recent Developments and Strategic Industry Moves
Recent market activities feature key product launches focused on brushless motor integration for extended tool life. Companies like Tubeex Engineering Private Limited have expanded their regional distribution agreements to capture rising demand in developing industrial corridors.